Six years in engineering. A growing focus on product strategy, credit and wealth.
A few numbers, real outcomes
Work that moved something forward.
A selection of outcomes from products and teams I’ve helped shape or build. My role is called out in each story.
₦400M+
Assets under management on Contree’s cooperative savings platform.
66→90%
SME loans approved within the 48-hour SLA at Moniepoint.
Near 0
Monthly credit-check failure complaints after the Moniedesk flow launched.
70%
Risey AI campaign scripts started with the AI generator I proposed and built.
Selected work
A few problems worth solving.
From navigating a licensing constraint to removing friction from credit operations, these projects show how I think about the problem before the interface.
WealthtechProduct strategy2024–25
Contree
When the obvious route was blocked, we found a different way to make saving and investing possible.
Contree Capital, the asset and wealth management arm of Forfond Group, wanted a consumer savings and investment app in the mould of PiggyVest and Cowrywise. As Technical Product Architect (contract, 2024–25), I co-designed with the founder the route that let it launch at all.
My role: co-designed the product strategy with the founder · designed the tenancy and configurable product rules
₦400M+Assets under management
300+Members, grown organically
₦1.3M+Average per member
2Cooperatives on the platform
01 / The constraint
A licensing wall
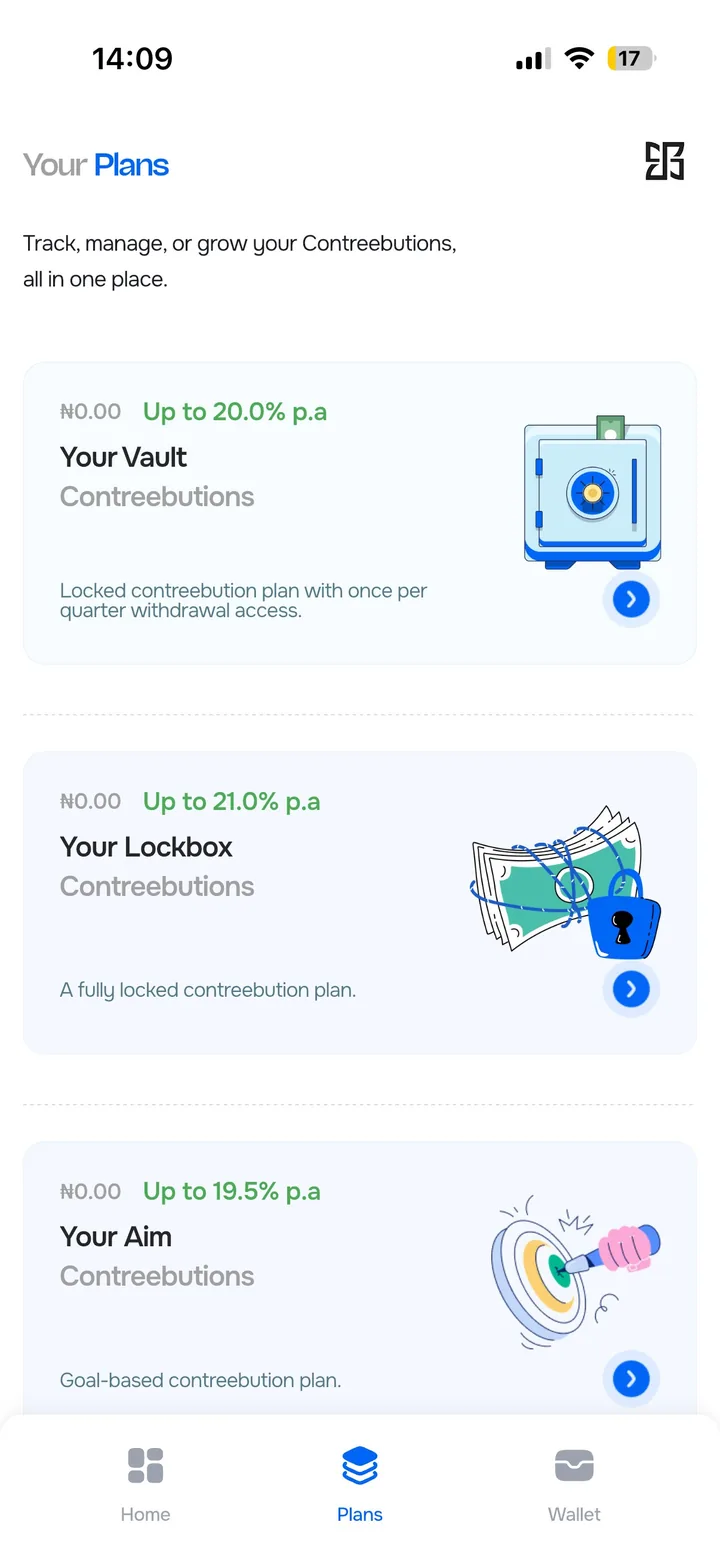
The plan was four savings products: AIM for target savings, Lockbox for locked funds, Flow for flexible savings, and Vault. But a consumer savings and investment product like this needs an SEC licence in Nigeria, which is slow, expensive and uncertain to get. The direct route was blocked.
02 / The reframe
Sell software to cooperatives instead
The insight: cooperative societies can legally pool members’ savings, pay interest and offer credit, but most of them run manually. So rather than becoming the regulated savings provider, we built in two layers:
A multi-tenant SaaS platform for cooperatives. Cooperatives sign up, configure their own savings products and invite members. Selling software needs no licence.
Forfond Cooperative Society as the first tenant. A cooperative licence was much easier to get than an SEC licence. Forfond’s cooperative runs on the platform, with AIM, Vault, Lockbox and Flow configured as its member products.
The trade-off: a platform that any cooperative can configure took more time and effort than a single savings app. We accepted it because the direct route couldn’t launch, and the platform became a sellable B2B product in its own right.
Why it held up: tenancy and configurable product rules were designed in from the start, so setting up Forfond’s products was configuration, not a rebuild.
03 / The member experience
A savings app on the surface
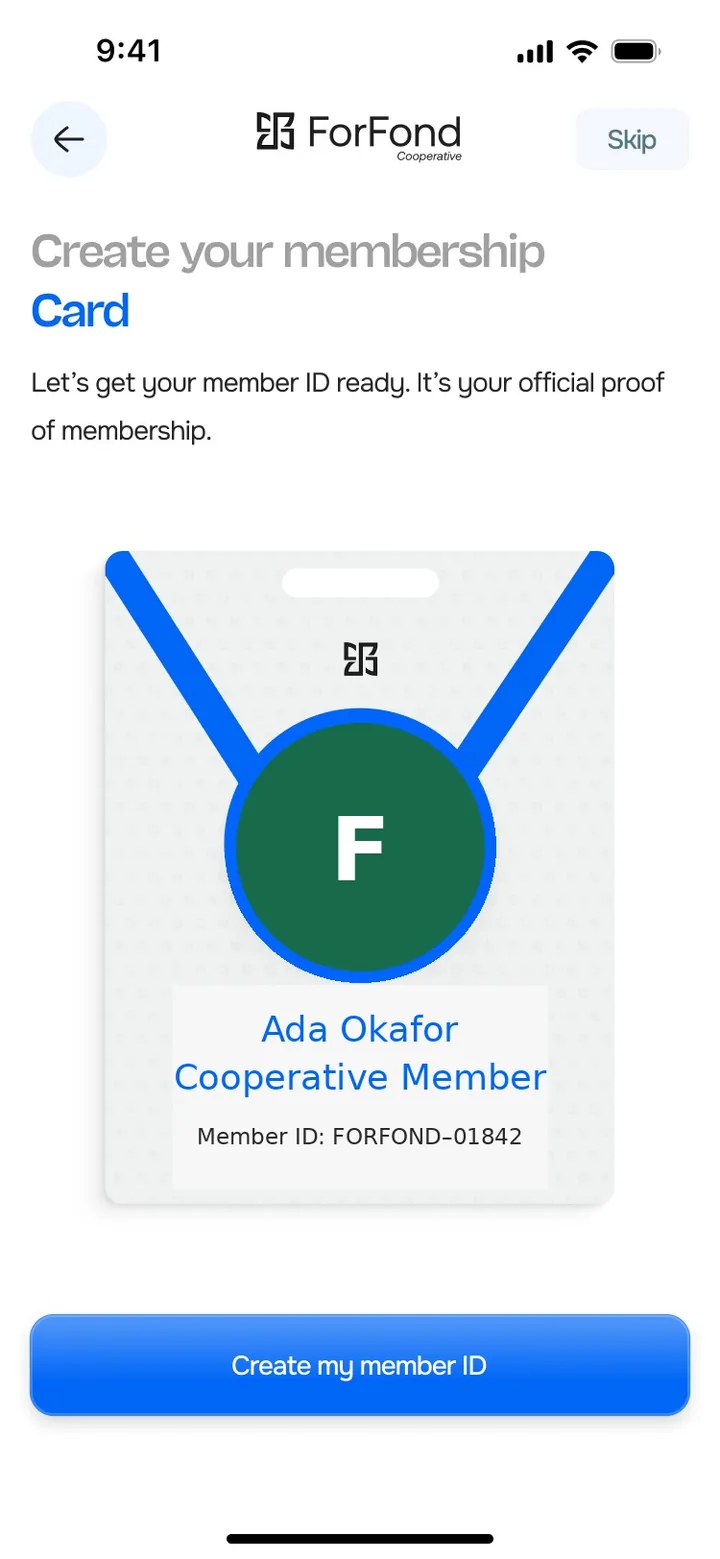
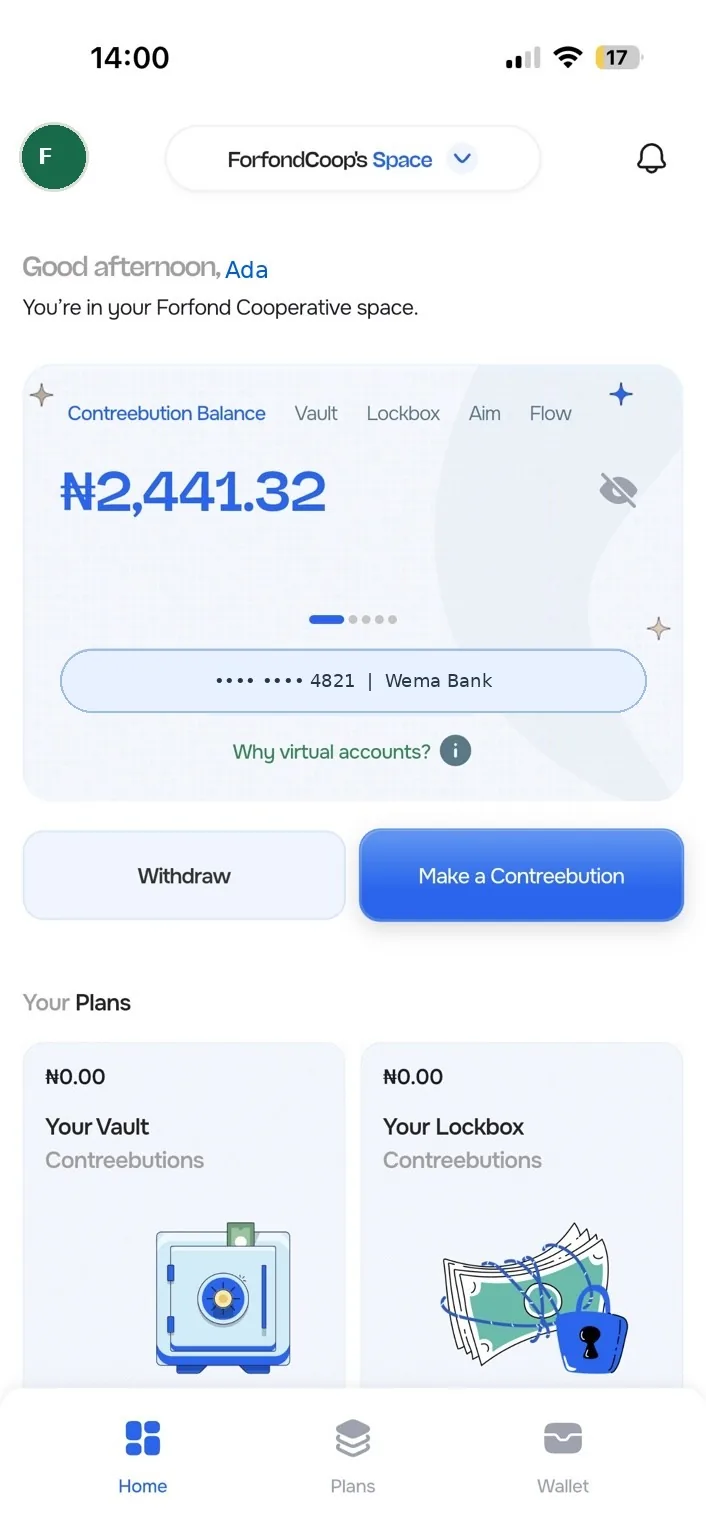
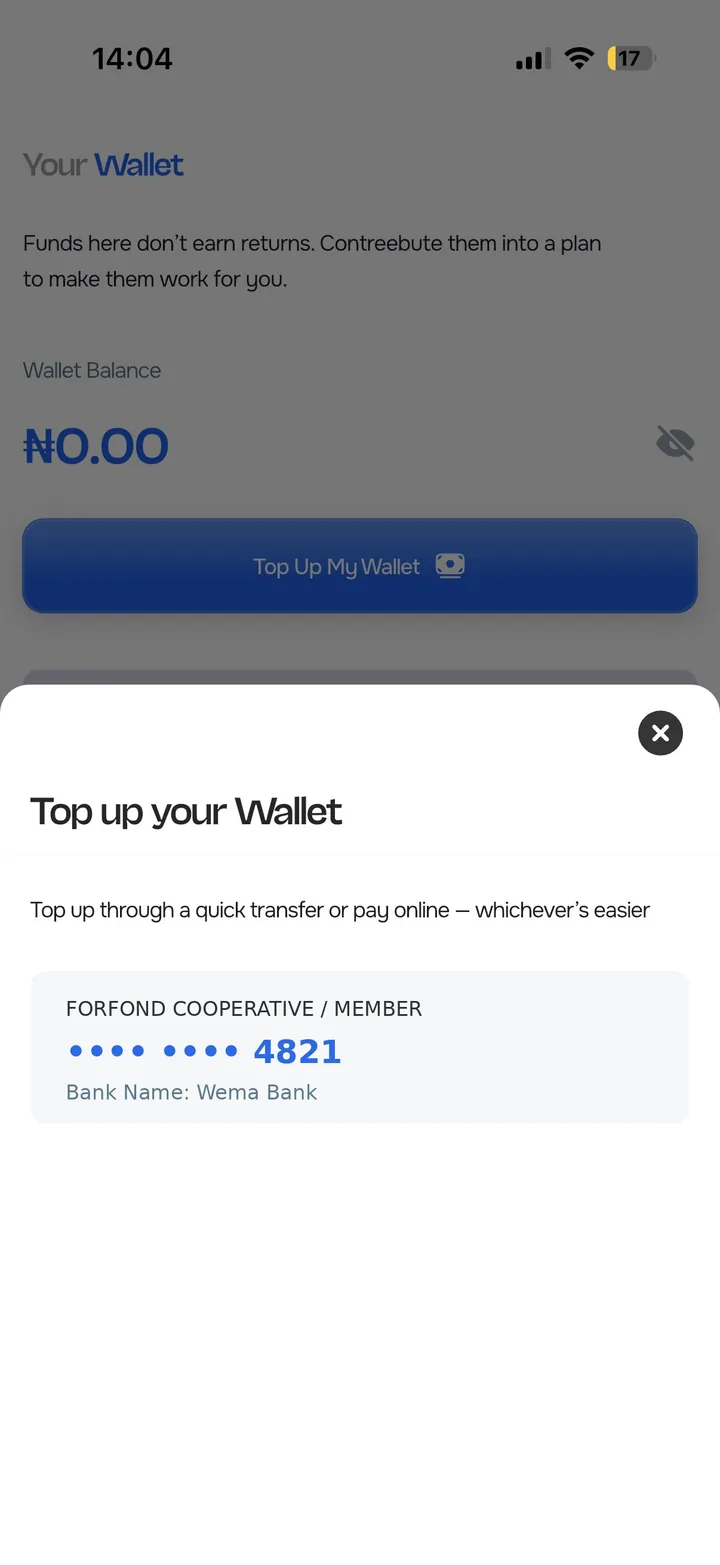
Members see a savings app; the cooperative structure stays mostly invisible. They join through a cooperative’s invite or sign up directly and choose a cooperative, complete KYC, and receive a member ID number and a downloadable member ID card. One person can belong to more than one cooperative, and each member gets a dedicated virtual account through Monnify to fund their savings.
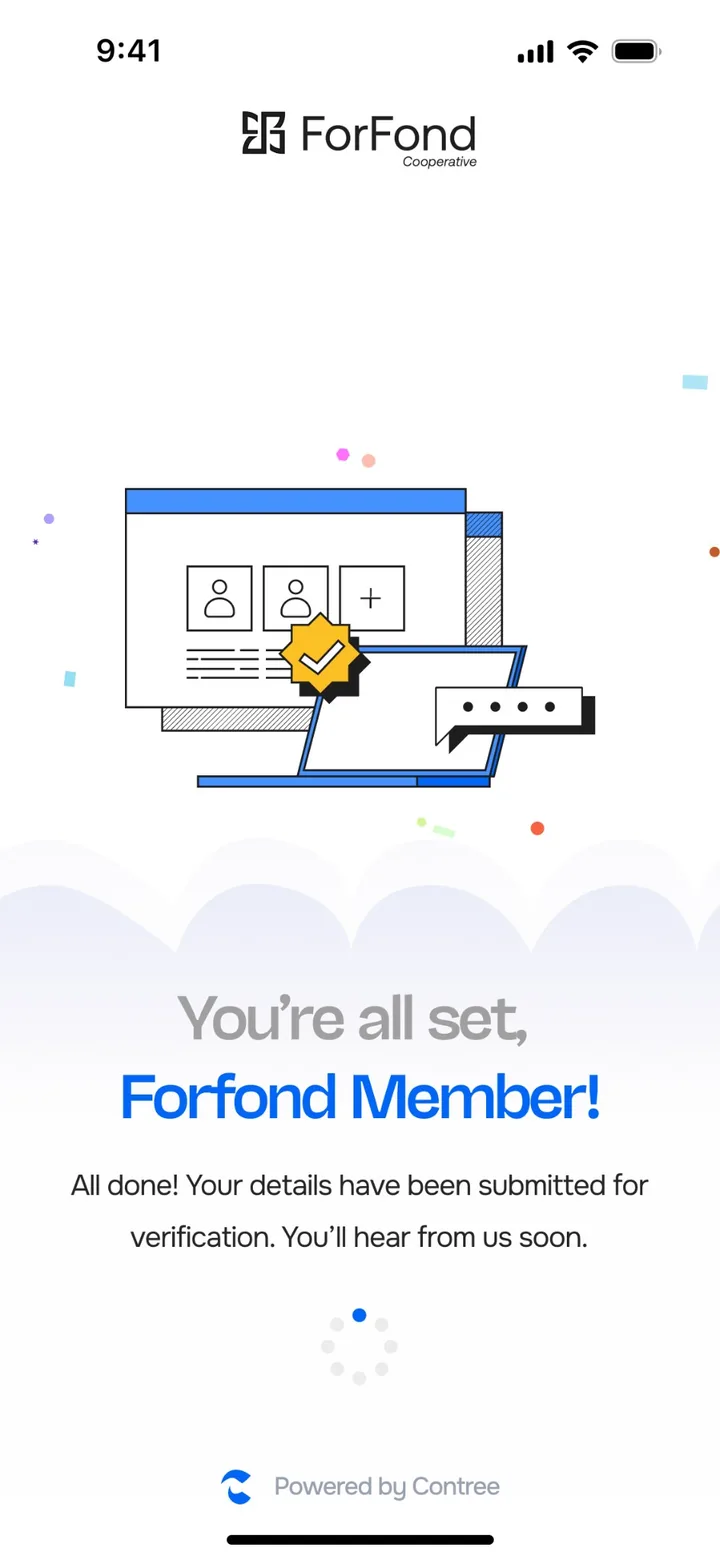
Wallet funding Virtual account top-up flow for cooperative members.Membership confirmation Clear feedback after a member submits their details for verification.
04 / Outcome
Launched, and grown organically
The platform reached ₦400M+ in assets under management and 300+ members, grown organically, averaging more than ₦1.3M per member. Two cooperatives now run on it: Forfond and one other.
When a constraint is fixed, the solution space usually isn’t. The key decision was changing who the customer was.
Moniepoint — Getting the right credit to the right businesses +
At Moniepoint I was a Senior Frontend Engineer on Credit Platforms (November 2025 – November 2026), building the tools that relationship managers, credit officers and loan operations use to get SME loans approved. This is where I learned credit as a business. Three pieces of work shaped how I think about it.
01 / Remote Loan Sales
Lending against the right business
My role: proposed the change · adopted by the product manager and shipped at launch
Context: Business Relationship Managers (BRMs) can start a loan request for a business owner from the BRM app. The owner receives a consent request, reviews the details and approves remotely.
The problem I spotted: Before launch, I noticed that eligibility and affordability were checked against the owner’s primary business, which isn’t always their most liquid one. An owner with a stronger secondary business could get a smaller offer or be rejected outright. The only fix was for the owner to change their primary business themselves and for the BRM to reapply, which defeated the purpose of a remote sale.
The decision: I proposed adding a step to the loan request flow so the BRM can review and update the owner’s primary business before submitting. The product manager adopted it and it shipped with the feature. To keep the owner in control, the consent screen shows every change the BRM made alongside the full request details.
Outcome: Larger loan amounts and fewer reapplications. Because the fix shipped at launch, the problem never reached users, so there is no before-and-after figure.
In credit, flow details decide who gets credit and how much.
02 / Credit-check failures
From five hand-offs to one review
My role: built it end to end
1,440–2,500Credit-check failure complaints a month, before
Near zeroAfter launch
Context: Every loan request includes a credit bureau check. Bureaus charge per query, so the team built a Financial Information Service (FIS) that caches bureau reports. Cached reports can be manually overwritten when newer information is available.
The problem: Cached data goes stale. A common failure was the bureau showing an existing loan with another bank that the owner had already repaid. Resolving it took five manual hand-offs:
The BRM contacts the business owner.
The owner gets a letter of non-indebtedness from the other bank.
The owner sends it to the BRM.
The BRM posts it to Moniedesk, Moniepoint’s support platform.
Support and loan operations pass it back and forth before the record is updated.
What I built: When a credit check fails, the BRM sees a “Notify merchant” button, which also works in remote sales. The owner is told which banks the bureau flagged and uploads a letter for each bank in the app. Each upload creates an override request; loan operations checks that the letter matches the flagged bank and approves it, and the approved override updates the cached record in FIS.
Outcome: Five hand-offs became one review step. Credit-check failure complaints on Moniedesk fell from 1,440–2,500 a month to near zero after launch.
Credit risk is also about not accidentally rejecting good borrowers.
03 / Cluster-based assignment
The right officer, close to the business
My role: mainly engineering · proposed making clusters configurable by operations
66% → 90%SME loans approved within the 48-hour SLA
The problem: Loan requests were often assigned to Field Credit Officers (FCOs) far from the business. That caused proximity-based rejections, manual reassignment and missed approval deadlines.
What was built: Local Government Areas (LGAs) were grouped into clusters, each with its own FCOs and Portfolio Managers. Requests are assigned automatically based on the business owner’s location, and FCOs are selected by workload and cluster capacity. Portfolio Managers can manually assign anything left unassigned, and leave handling with backup Portfolio Managers covers staffing gaps.
My proposal: make clusters configurable by the operations team, so they could run it without engineering. In the Loans back-office app, operations creates clusters, adds Portfolio Managers, FCOs and LGAs, sets capacity, marks officers on leave and assigns backups.
Outcome: SME loans approved within the 48-hour SLA rose from 66% to 90%.
Speed in credit depends on getting the right person to the right borrower, and on designing for absences.
Company-reported context
Credit at SME scale
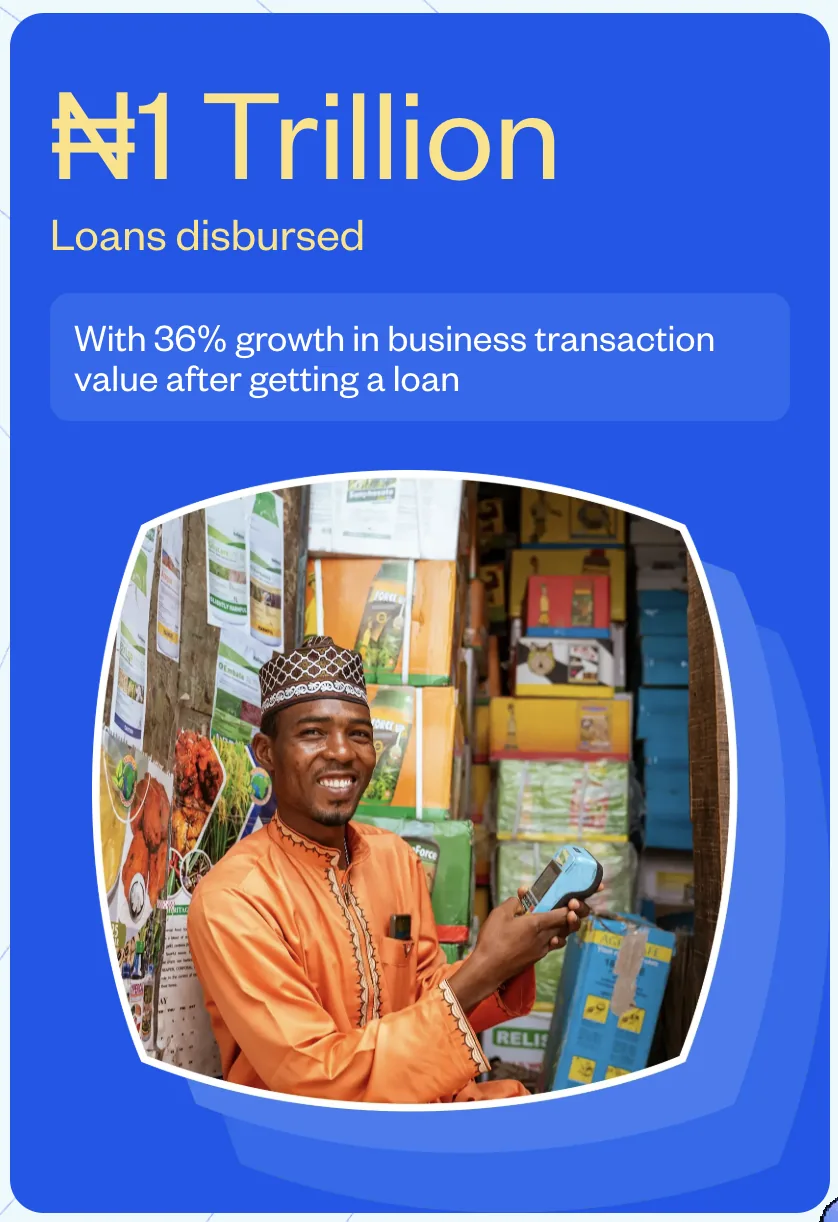
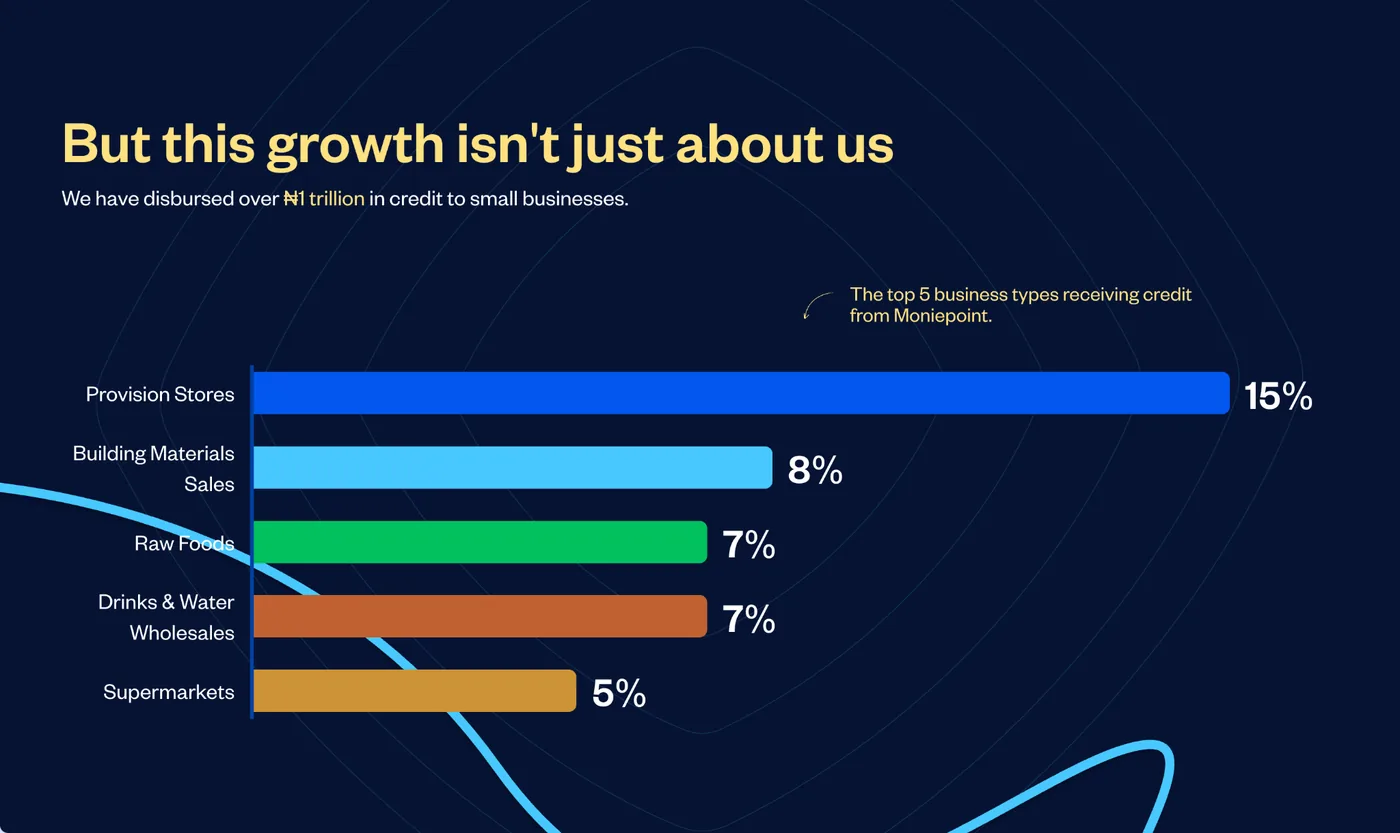
Moniepoint has disbursed over ₦1 trillion in credit to more than 70,000 businesses, and business lending was the company’s biggest growth driver over the past year. These company-level results set the context for the work above. They are not outcomes attributed to my individual work.
₦1 trillion+ in loans disbursedCompany-level lending impact reported by Moniepoint.Who the lending ecosystem servesCompany-reported distribution across business categories.
Risey AI — Solving the blank-page problem +
Risey AI is a marketing SaaS for Shopify store owners. It delivers personalised audio campaigns in the owner’s own AI-cloned voice. I was Technical Lead from January to October 2025, working remotely for the Birmingham-based team.
My role: proposed, designed and built the AI script generator · led voice AI vendor evaluation and integration
01 / The product
A store owner’s voice, on their storefront
Risey has three parts:
Storefront widget: a personalised voice note, such as greeting a signed-in customer by name and offering a discount code. It can appear on the landing page, product pages or checkout, with different widgets on different pages.
Admin dashboard: where owners configure their cloned voice, campaigns, and the widget’s appearance and placement.
Voice cloning: the owner uploads a voice sample, the product generates clones at different voice settings, and the owner picks one.
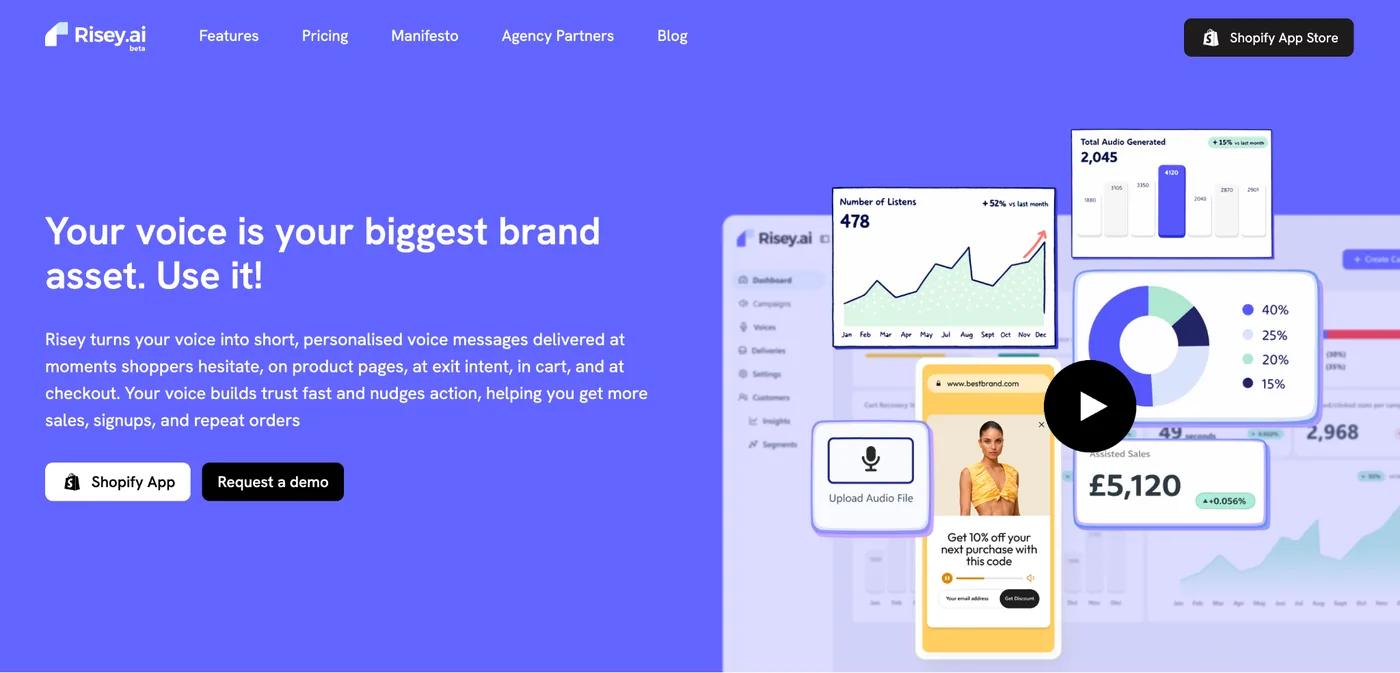
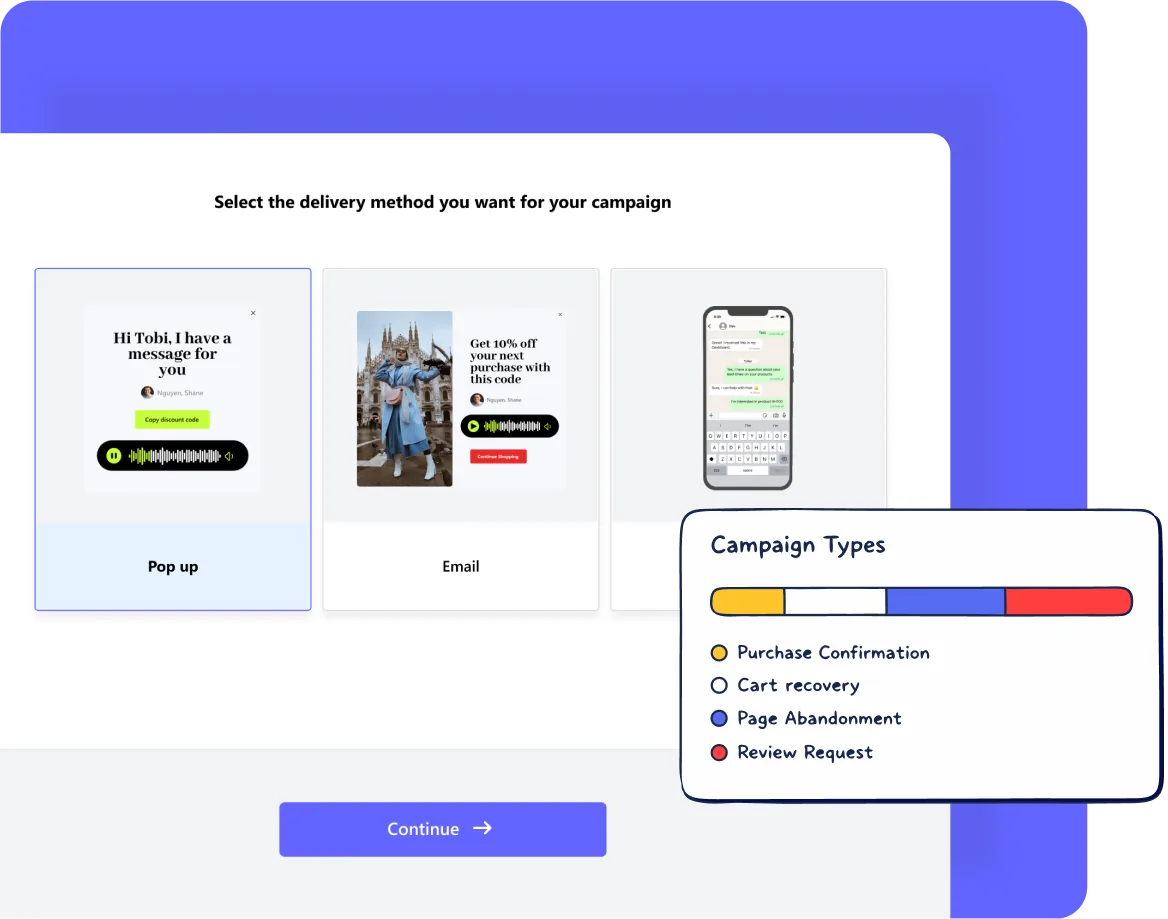
How Risey is pitchedThe Risey.ai homepage, aimed at Shopify merchants.Campaign setupOwners choose how a campaign reaches customers.
02 / The key decision
Getting merchants past the blank page
My idea · proposed, designed and built
70%Of campaign scripts were AI-generated
The problem: every campaign started with an empty script box, and most store owners aren’t copywriters. The headline feature was the cloned voice, but the step just before it was where people stalled.
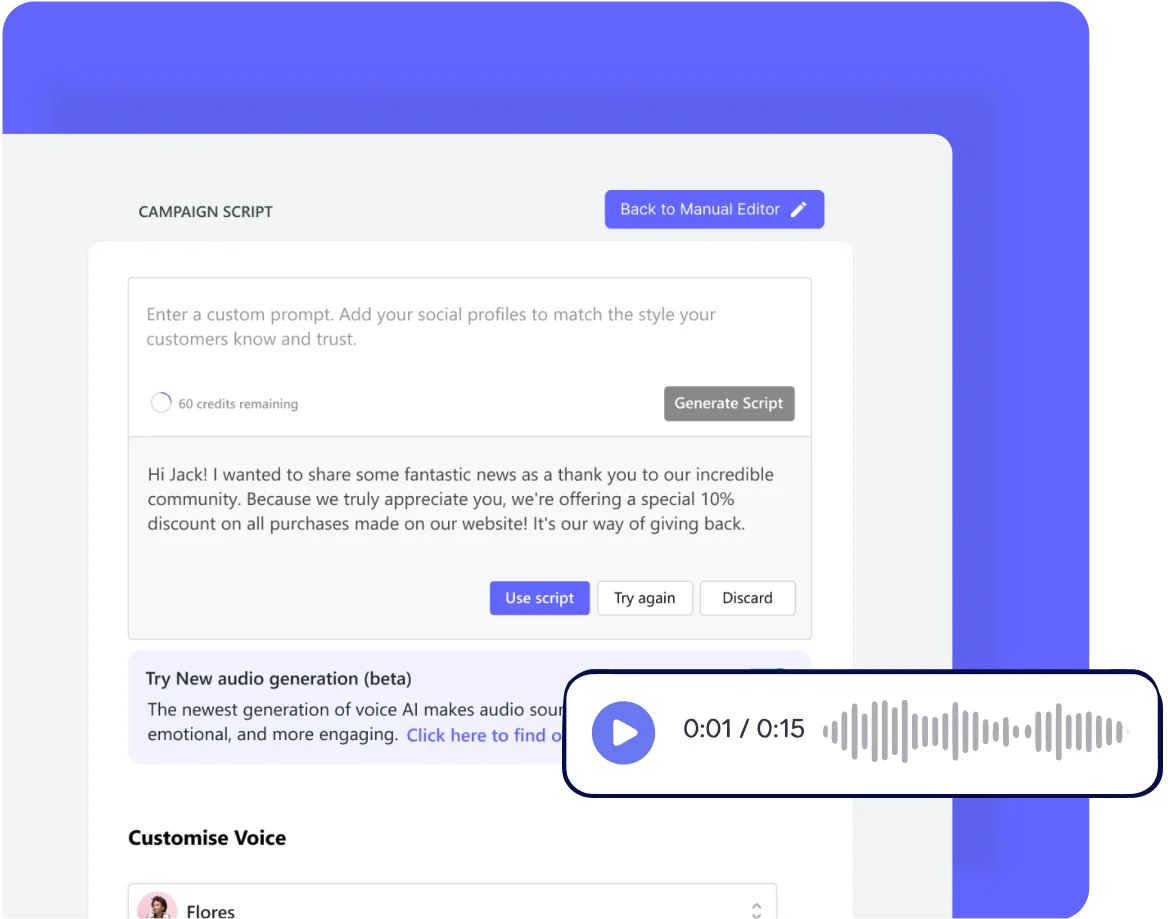
What I built: a “Generate script with AI” button. It scrapes the owner’s storefront for context, such as products and landing-page content, combines it with a marketing-focused prompt for the campaign type, and drafts a script the owner can edit, use or try again.
Outcome: 70% of campaign scripts were AI-generated. It also made Risey feel AI-native beyond voice cloning.
AI script editorA product-aware draft the owner can use, regenerate or discard.
03 / Vendors and early customers
Choosing the voice, listening to the market
Vendor evaluation: I compared ElevenLabs and Speechify for voice cloning. ElevenLabs was the better fit for the use case, and its startup credits also reduced early costs. I led the integration.
Customer research: I demoed Risey to a UK influencer who runs a Shopify store, and he became one of the first customers. His feedback was that a widget that doesn’t match the store’s look reads as a spammy pop-up, so we added font and colour customisation.
The step users stall on is often the one just before the headline feature.
He-brews — Launching to learn before monetising +
New and Living Way Church publishes Hebrews, a daily devotional, in print. Leadership wanted a digital version with premium features behind a subscription from day one. As Product Lead, I’m leading a four-person team (an engineer, a designer, a UX writer and me) towards a January 2027 launch.
My role: Product Lead · scoped the MVP, wrote the decision documents, leading the team
FreeAt launch, with no sign-up
4-personCross-functional team
Jan 2027Launch date
01 / The real goal
A daily habit, not a digital copy
The brief was a digital version of the book. The real goal was to build a culture of daily consistency in fellowship, with people coming back every day. That shaped the MVP: features that bring readers back each day, and as little as possible standing between them and the reading.
02 / The key decision
Launch free, then let behaviour decide the paywall
The tension: leadership wanted to choose the premium features upfront. Before launch, that would mean guessing what readers value.
My recommendation: launch free, with no sign-up and no subscription, and use real reader behaviour to decide what goes behind a subscription later.
How we got to yes: for each feature, I wrote a decision document setting out the question, the options, my recommendation and my reasoning, and asked leadership for direction. Every recommendation was adopted, including the free launch.
03 / The MVP
What readers get on day one
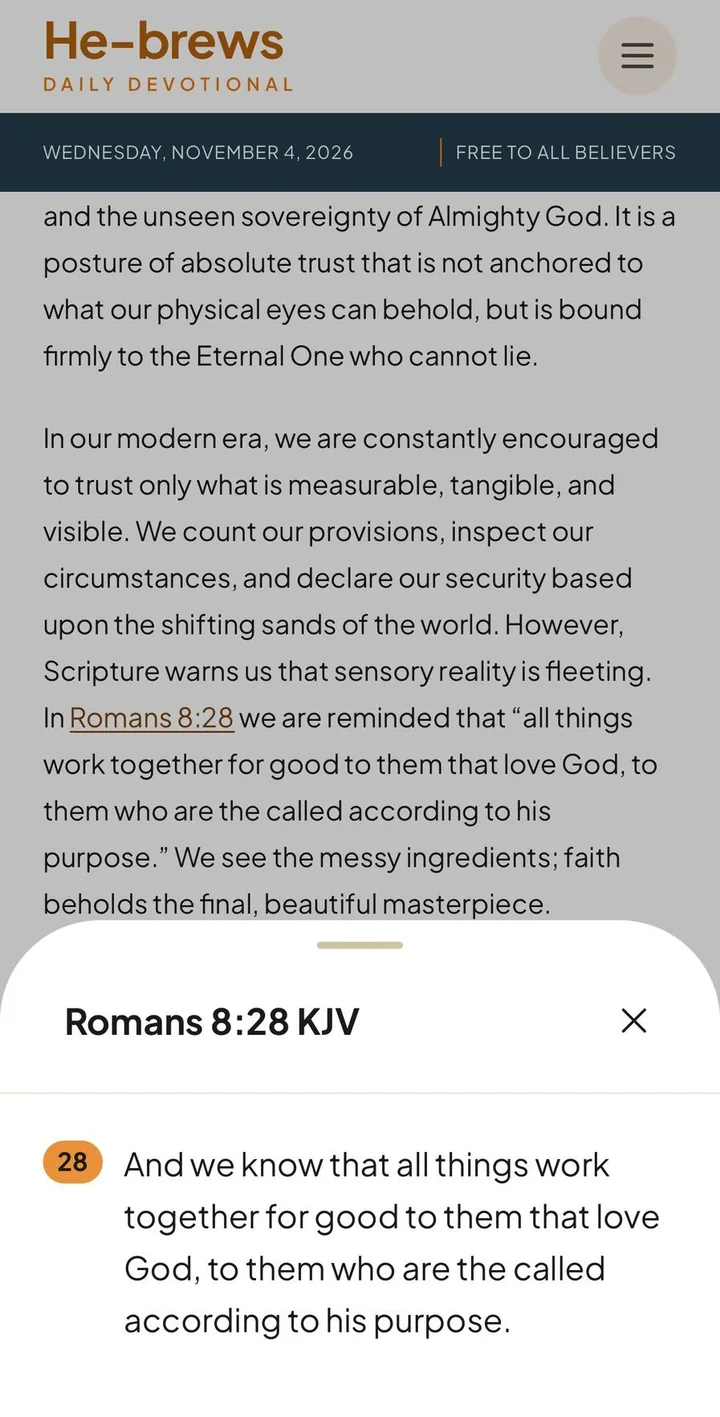
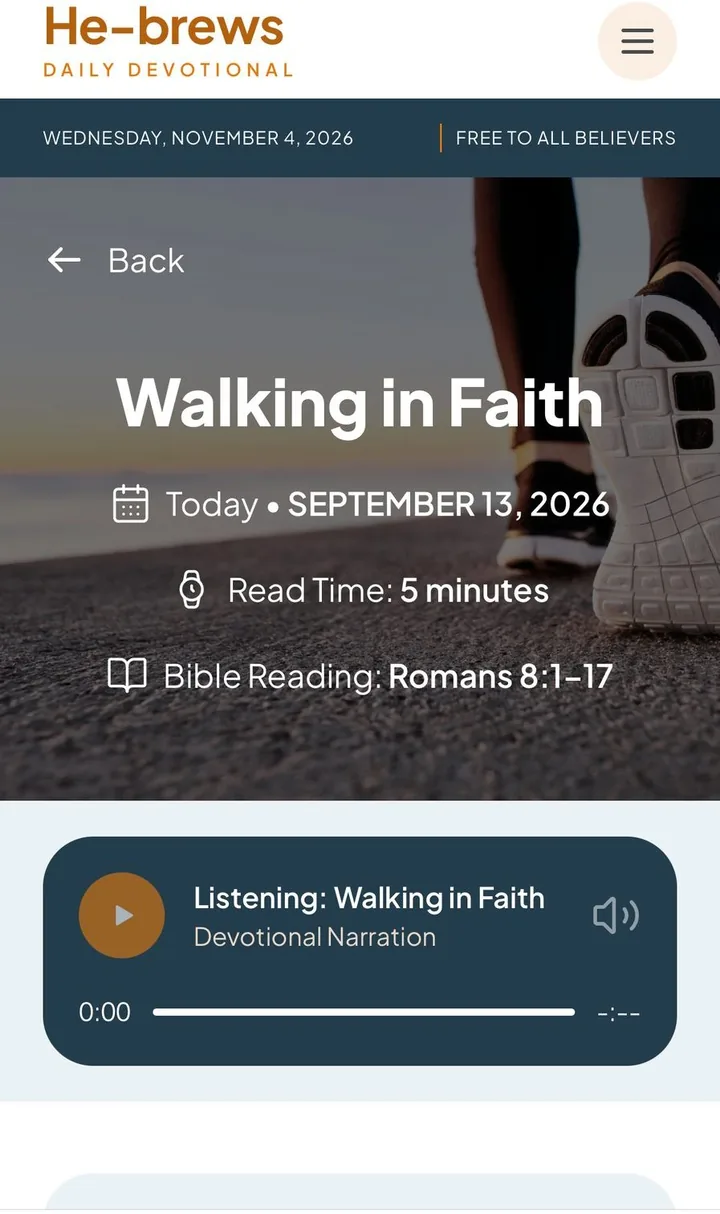
Read today’s devotional, with Bible references that open in place.
Listen in an AI-generated voice of the head pastor, with his consent documented in my proposal to leadership.
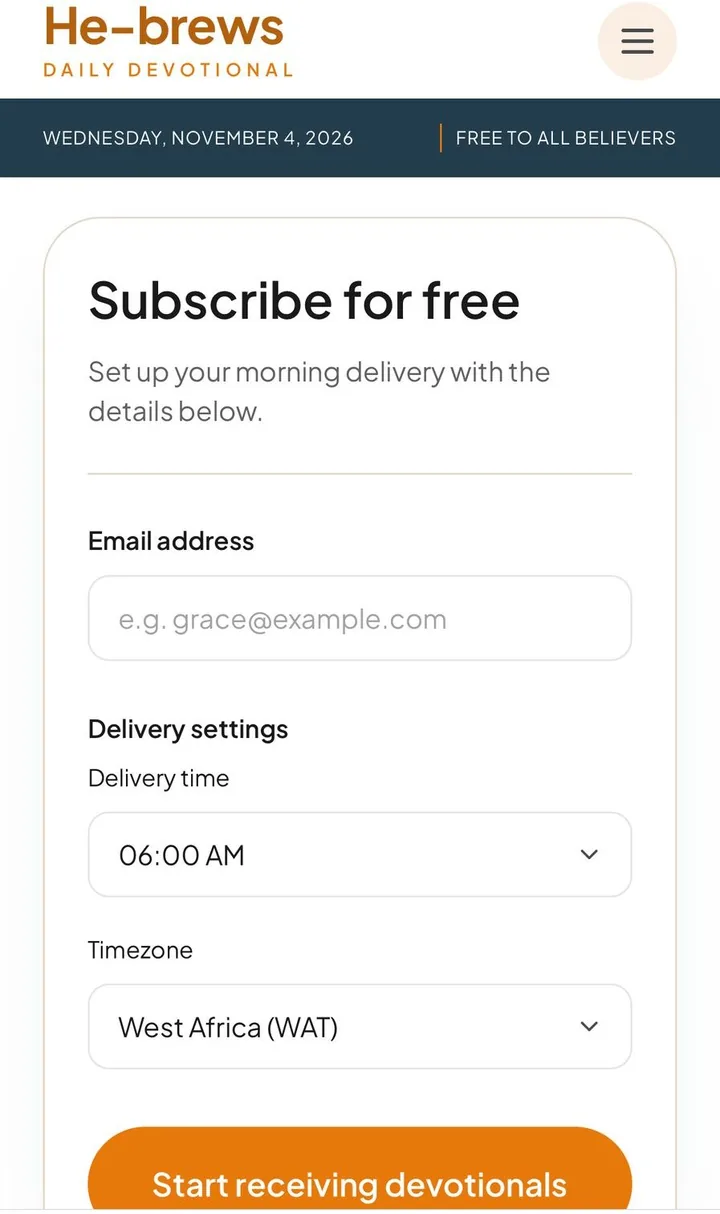
Get it by email every day, at a chosen time and timezone.
Receive a push notification when each new devotional goes live.
Search, and catch up on missed days in the archive.
Highlight a passage and turn it into a shareable image for social media.
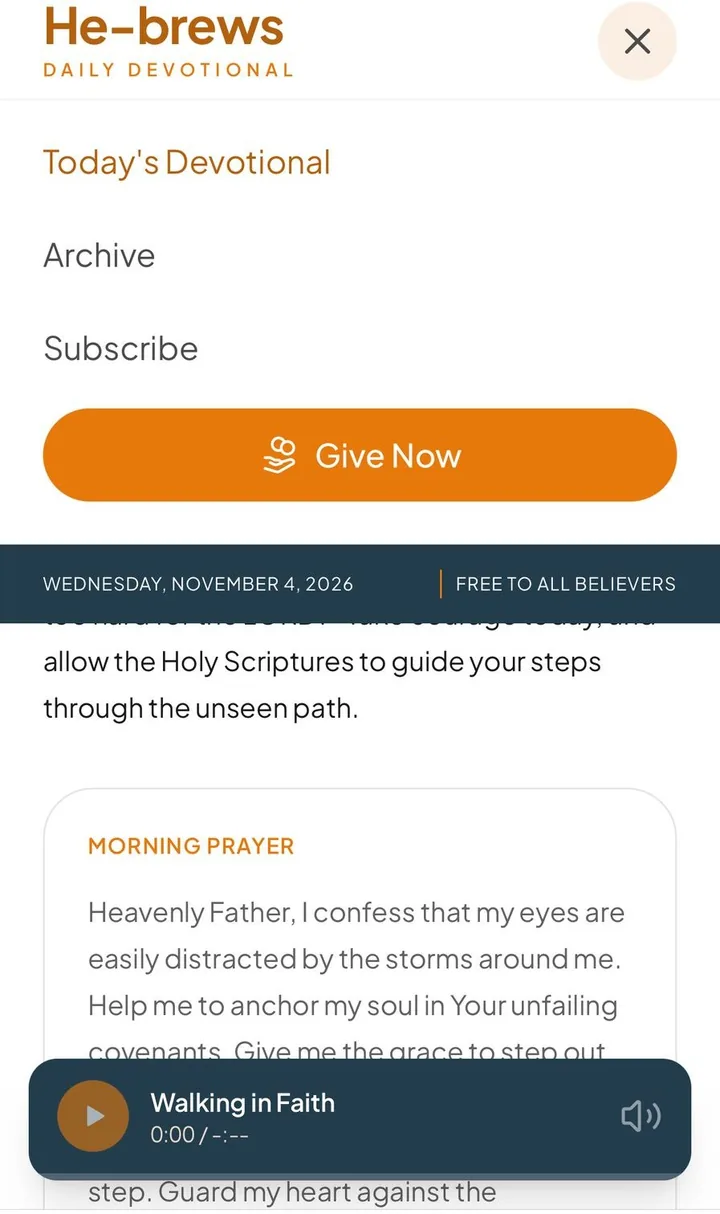
Daily devotionalReading page with estimated read time and audio narration.Clickable Bible referencesReaders can open a referenced KJV passage without leaving the devotional.Email subscriptionReaders can configure a preferred delivery time and timezone.Navigation and discoveryAccess today's devotional, archive, subscription and giving.
04 / Funding and what’s next
Paying for it before the paywall
Giving from day one: a “give / support the work” prompt appears after a reader finishes the day’s devotional, so the product has funding from launch without a paywall.
Pricing, when subscriptions come: $1 per quarter, one payment per quarterly release. That’s low enough not to deter a daily habit.
Sequenced after the MVP: sign-up, subscriptions, reading streaks, and participation and encouragement prompts.
Status: in development for a January 2027 launch, so there are no usage results yet.
Stakeholders resist uncertainty more than ideas. Written recommendations with trade-offs turn opinions into decisions.
How I approach product
A few beliefs I bring to the product table.
Good product work is rarely about having the loudest idea. It’s about asking a better question, making a clear choice and learning from what happens next.
01 / REFRAME
Constraints are fixed. Solutions are open.
When a direct-to-consumer investment route hit a licensing wall, we explored a cooperative SaaS model instead.
↗02 / OBSERVE
Look at the step before the feature.
Sometimes the biggest friction isn’t the feature itself. It’s the blank page before someone can use it.
◎03 / DECIDE
Make the decision visible.
Write down the question, options, trade-offs and recommendation. Alignment gets easier when the thinking is clear.
↗04 / MEASURE
Let behaviour challenge opinion.
Launch the simplest useful version, learn what people do, then earn the right to add complexity.
◌
For six years, I’ve built fintech and digital products as an engineer, mostly alongside product teams. Over time, I found myself most drawn to the work that happens before development starts: understanding the customer problem, finding the opportunity, defining the solution and deciding what matters most.
My engineering background is a foundation, not a detour. I understand what it takes to build and scale a product, and I can work with engineers as a peer. I’m now focused on bringing that perspective to credit, savings and investment products.
Senior Frontend Engineer · Moniepoint
SME lending, credit operations and workflow improvements.
Technical Lead · Risey AI
AI-powered marketing SaaS for Shopify merchants.
Technical Product Architect · Contree
Co-designed a cooperative savings and investment platform.
Senior Software Engineer · Studio 14
Digital products for clients including UNICEF, across 20 countries.
Product Lead · He-brews
Leading discovery and MVP decisions for a digital devotional launching in 2027.
Have a product problem worth solving?
Let’s make something matter.
Interested in credit, wealth and fintech products. Based in Lagos · Open to remote opportunities.